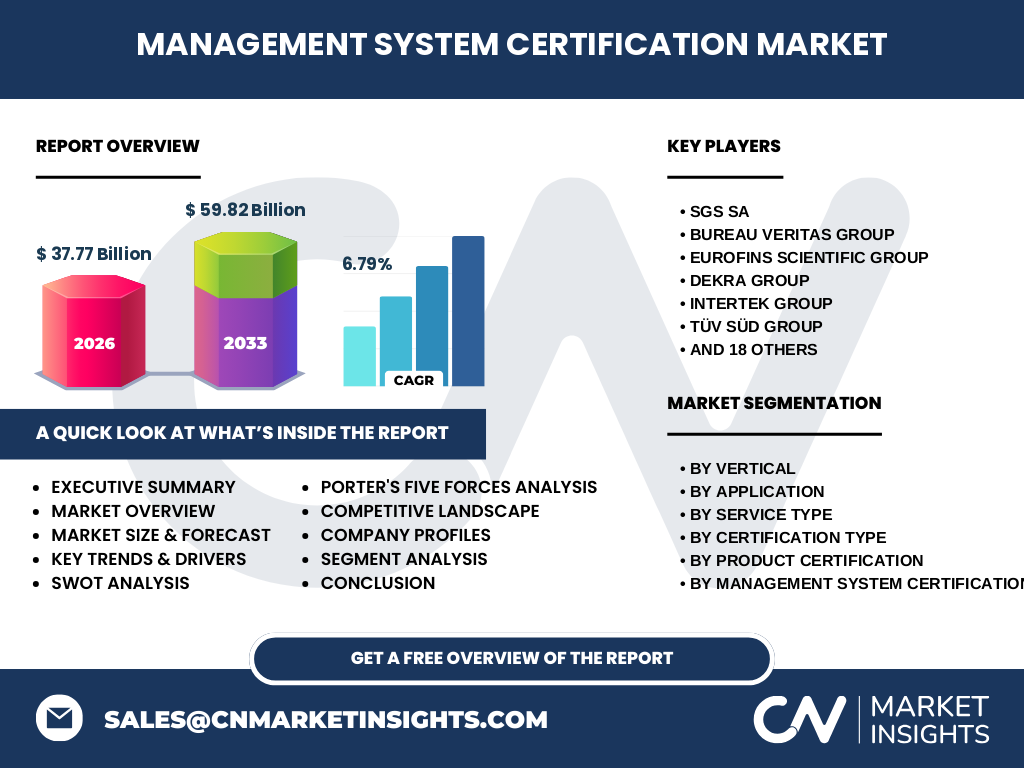
Market overview of the Management System Certification Market
Our analysis indicates that the Management System Certification Market achieves a valuation of $37.77 Billion in 2026. This sector encompasses critical verification services governed by bodies like ISO, ensuring operational compliance across complex global supply chains for raw materials and finished goods.
Structural Growth Drivers and Restraints
The market is propelled by stringent regulatory mandates from bodies like OSHA and the EPA. Key growth drivers include escalating supply chain transparency demands, while high initial auditing costs and complex multi-site verification processes act as notable operational restraints for heavy industries.
Emerging Industry Trends
Digital transformation is reshaping auditing practices. Remote surveillance audits and AI-driven compliance tracking are gaining traction, allowing major players to streamline verification across high-risk sectors like oil, gas, and chemical manufacturing without sacrificing analytical rigor.
COVID-19 Impact and Recovery Trajectory
The pandemic severely disrupted on-site auditing schedules, forcing a rapid pivot toward virtual assessment methodologies. Post-pandemic recovery has accelerated robustly, driven by a renewed corporate focus on operational resilience, supply chain continuity, and occupational health standards.
Competitive Benchmarking and Industry Concentration
Market concentration is moderately high, anchored by global powerhouses like SGS SA, Bureau Veritas Group, and DEKRA Group. These leaders leverage extensive global laboratory networks and accredited personnel to secure enterprise-wide contracts across manufacturing and energy sectors.
Executive Summary of the Report
Driven by robust demand for quality and safety compliance, the Management System Certification Market is projected to surge from $37.77 Billion in 2026 to $59.82 Billion by 2033, expanding at a solid 6.79% CAGR over the forecast period.
Market Forecast Analysis (2027 to 2033)
Based on our research, the market will expand from 2027 through 2033 to reach $59.82 Billion, maintaining a steady 6.79% CAGR. This expansion is fueled by rising corporate ESG commitments and mandatory environmental management frameworks.
Comprehensive Segmentation Analysis
Our segmentation breaks down the market by vertical (Consumer Goods, Agriculture, Energy, Mining, Public), Application (ISO 9001, ISO 14001, Cyber Security), Service Type (Certification, Training), and Certification Type. Industrial and Manufacturing alongside ISO 9001 quality frameworks represent the largest revenue-generating nodes.
Geographic Distribution and Regional Performance
Regional performance varies significantly, with Europe maintaining dominance due to stringent European Union regulatory directives, followed by rapidly expanding industrial hubs across Asia-Pacific driven by manufacturing growth in nations like China and India.
In-Depth Regional Market Review
North America exhibits high demand for information security and occupational health certifications, whereas Asia-Pacific focuses heavily on product safety and environmental management compliance to meet international export criteria set by destination markets.
Strategic Company Profiles
Leading entities such as Intertek Group, TÜV SÜD Group, and DNV GL Group focus on strategic acquisitions of niche tech-auditing firms. This positioning allows them to capture emerging demand in cybersecurity and renewable energy verification.
Porter's Five Forces Assessment
The threat of new entrants remains low due to high accreditation barriers and required technical expertise. Bargaining power of buyers is moderate to high, as large multinational corporations demand customized, integrated audit solutions across diverse global facilities.
SWOT Analysis of the Sector
Key strengths include established global accreditation frameworks. Weaknesses involve pricing pressure from smaller regional auditors. Opportunities lie in digital ESG reporting, while regulatory shifts represent persistent external threats.
Value Chain Analysis
The value flow initiates with accreditation bodies and standard developers, moves through tier-one certification providers like British Standards Institution Group and TÜV Rheinland Group, and terminates at end-user industrial and public sector clients requiring verified compliance.
Investment Insights and Strategic Recommendations
High-potential investment areas center on digital auditing platforms and specialized cybersecurity certification services. Investors should target mid-sized compliance firms possessing proprietary software capabilities to capture high-margin advisory revenues.
Conclusion and Strategic Takeaways
The Management System Certification Market offers lucrative expansion avenues, anchored by a 6.79% CAGR. Stakeholders must embrace digital audit tools and sustainability frameworks to maintain competitive differentiation.
Research Methodology and Data Triangulation
Baseline estimates are triangulated by synthesizing primary stakeholder interviews with C-level executives, secondary trade registry data from international accreditation forums, and macroeconomic indicators impacting global industrial manufacturing outputs.
Scope of the Report and Limitations
This report covers global market dynamics from 2026 to 2033, analyzing service types, verticals, and application areas. Limitations include potential unforeseen geopolitical shifts affecting cross-border trade and localized regulatory compliance mandates.
Recent Industry Developments and Strategic Moves
Recent market activity features aggressive partnerships between major testing groups like Eurofins Scientific Group and software providers to automate ISO compliance tracking, alongside expansion into green energy auditing by firms such as Kiwa Group.